A business can be profitable and still run out of cash.
That is one of the hardest lessons many founders learn.
Revenue growth looks encouraging. Sales are increasing. New staff are joining. Customers are happy.
But if cash is arriving too slowly, leaving too quickly or being committed without a clear forecast, growth can become more dangerous than decline.
The difference between a business that simply survives and one that scales sustainably often comes down to cashflow hygiene.
Here are five common cashflow traps we see founders fall into — and how to avoid them.
1. Confusing Profit With Cash
Profit and cash are not the same thing.
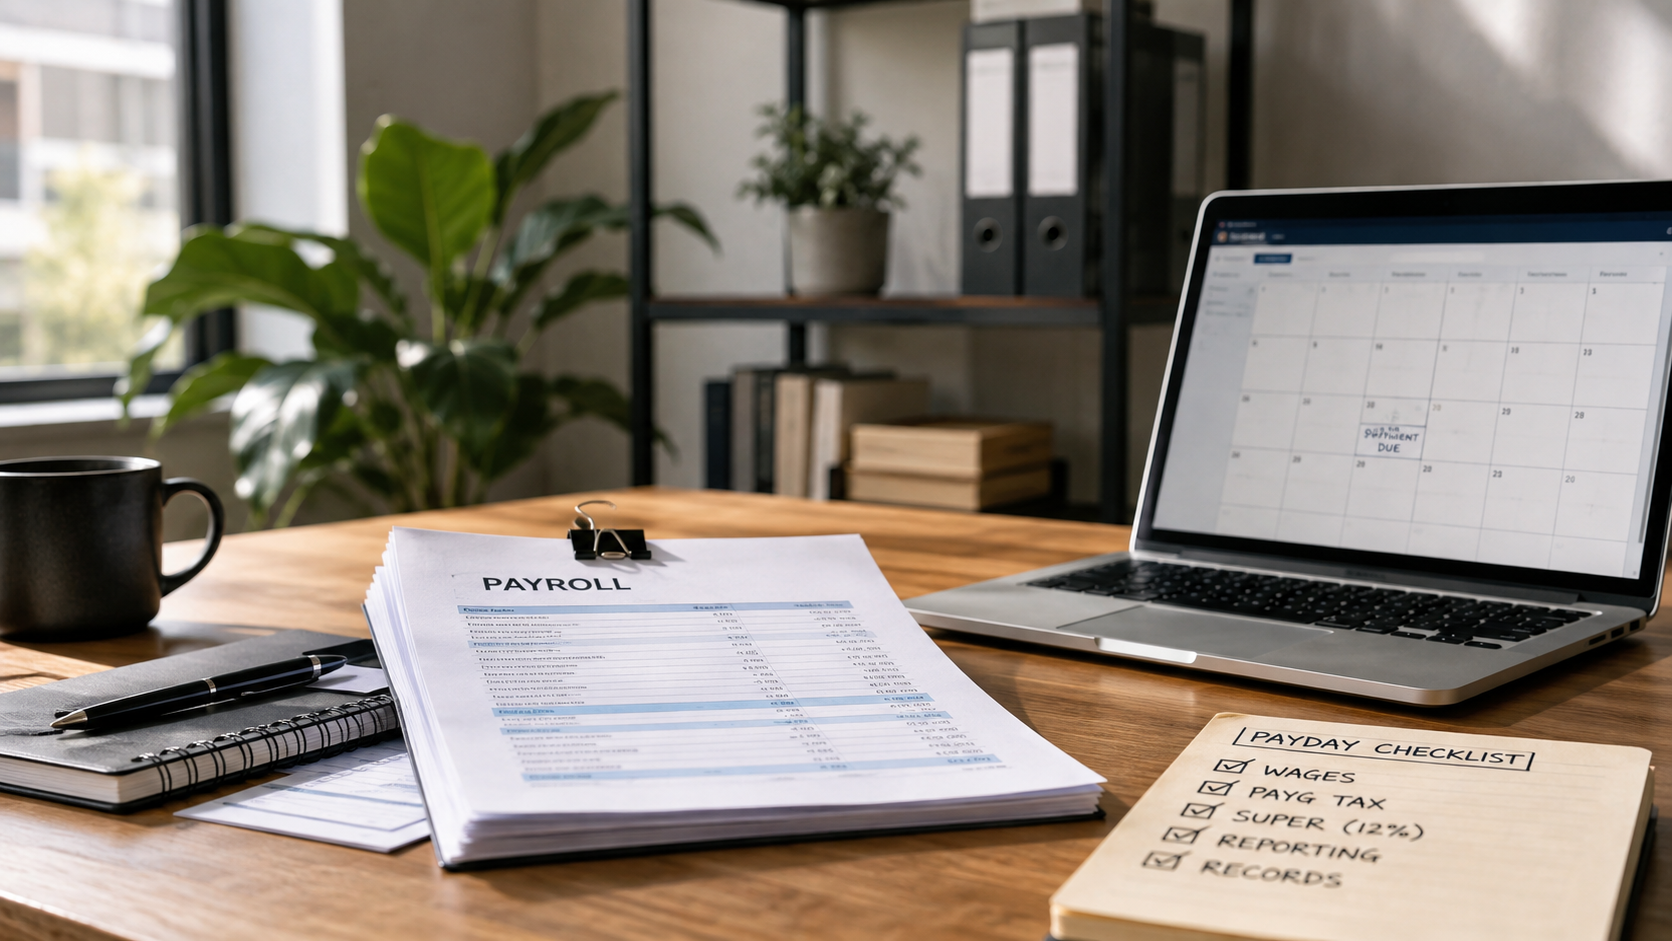
A business might invoice $100,000 in a month and record a healthy profit, but if customers take 45 or 60 days to pay, that money is not yet available to cover payroll, rent, suppliers or tax.
This becomes even more dangerous during periods of rapid growth.
More sales can mean more staff, more stock, more software and higher operating costs — all before the corresponding customer cash arrives.
The solution is simple in principle:
Track cash separately from profit.
Founders should regularly review:
- bank balances;
- accounts receivable;
- upcoming supplier payments;
- payroll commitments;
- tax liabilities; and
- expected receipts.
A profit and loss statement tells you whether the business is making money.
A cashflow forecast tells you whether the business can pay its bills.
You need both.
2. Letting Customers Set Your Payment Terms
Many founders focus heavily on winning work and not enough on collecting cash.
This often leads to generous payment terms, delayed invoicing and weak follow-up.
A job may be completed today, invoiced next week and paid 30 or 45 days later.
That means the business could be funding the customer for more than a month.
For service businesses, this can create significant pressure because wages are often paid weekly or fortnightly while customer cash arrives much later.
Better cashflow discipline includes:
- invoicing as soon as work is completed;
- using deposits or upfront payments where appropriate;
- setting clear payment terms;
- automating invoice reminders;
- offering simple payment options; and
- following up overdue invoices consistently.
The longer an invoice remains unpaid, the more working capital is tied up outside the business.
3. Spending Growth Before It Arrives
Founders are naturally optimistic.
That can be a strength.
But optimism becomes risky when future revenue is treated as if it is already in the bank.
A business may hire three new employees because a large customer is “almost confirmed”, take a larger office because growth is expected, or commit to new software and marketing contracts based on forecast sales that have not yet materialised.
The issue is not investing in growth.
The issue is committing fixed costs too early.
Before making a major expenditure decision, ask:
What happens if the expected revenue is delayed by three months?
What happens if sales come in 20% below forecast?
How much cash buffer remains after the commitment?
Scenario planning turns a hopeful growth decision into a financial decision.
4. Treating Tax Money as Operating Cash
One of the most common cashflow mistakes is looking at the bank account and assuming all of the money belongs to the business.
It often does not.
Depending on the business, part of that balance may effectively be committed to:
- GST;
- PAYG withholding;
- income tax;
- superannuation; or
- payroll tax.
If that money is used to fund everyday operations, the problem usually becomes visible when a BAS, super or tax payment falls due.
The business then has to find cash quickly.
A better approach is to treat tax obligations as committed cash from the moment they arise.
Some businesses use separate bank accounts for tax and super amounts. Others build them directly into weekly cashflow reporting.
The method matters less than the discipline.
Tax should be planned.
Not discovered.
5. Growing Without a Cashflow Forecast
Many founders manage cash by checking the bank balance each morning.
That tells you where you are today.
It does not tell you where you will be in six weeks.
A rolling 13-week cashflow forecast is one of the most practical financial tools for a growing business.
It should include expected:
- customer receipts;
- payroll;
- supplier payments;
- rent;
- tax and super;
- loan repayments;
- software and subscriptions;
- capital expenditure; and
- other major commitments.
A good forecast helps management identify pressure before it becomes urgent.
For example, the business may discover that a BAS payment, monthly payroll and annual insurance renewal all fall in the same week.
That gives the founder time to manage collections, delay non-essential spending or arrange funding early.
Without a forecast, the same problem feels like a surprise.
The Practical Takeaway
Most cashflow problems do not begin with one dramatic mistake.
They build quietly.
A few customers pay late.
A new hire starts early.
Tax is left in the operating account.
Expenses increase faster than revenue.
Then suddenly the business feels short of cash despite appearing profitable.
The solution is not complicated financial theory.
It is consistent cashflow discipline.
Founders should know:
What cash is coming in?
What cash is going out?
What is already committed?
What happens if the forecast is wrong?
That visibility creates better decisions.
At The Weft Advisory, we help growing businesses build practical cashflow forecasts, working-capital controls and financial reporting that show what is coming before the bank account does.
Because scaling successfully is not only about growing revenue.
It is about making sure the cash is there to support the growth.